A wholesale distributor can quote the same panels to two buyers and perform very different work. One buyer orders approved product codes and arranges collection. Another expects coordinated finishes, several sample rounds and scheduled deliveries. Consequently, the same material margin does not describe the resources each account consumes.
For an importer serving contractors and regional dealers, a useful quotation process connects prices to the promised support. The aim is to understand each commitment before accepting it, then compare the estimate with actual work.
Quick Answer: What Should a Distributor Measure?
Measure sales revenue, the defined landed material cost and the support costs attributable to the project. Then calculate the amount remaining after those identified costs. Keep that measure separate from material gross margin and company profit. Quote a clear service scope, require approval for discounts that reduce the remaining amount below an internal threshold, and update assumptions with recorded activity after delivery.
Define the Two Numbers Before Comparing Accounts
For this purchasing worksheet, define material gross margin as sales revenue minus the landed material cost assigned to the order. Include the agreed inbound freight and handling basis consistently. Divide that difference by sales revenue to express it as a percentage. Also, state whether a delivery charge sits in revenue or offsets a delivery cost.
Next, define project contribution after support as material gross margin minus the identified project support costs. This internal decision measure does not equal company profit: it may exclude shared overhead, finance costs and taxes. Have the business’s finance team reconcile its categories with existing reporting and prevent double counting.
ACCA describes using activity information to examine costs associated with customers. That principle supports tracing support work instead of judging an account only by sales volume. See its activity-based management guidance.
Trace the Support That the Quote Promises
Start with a few observable activities. Record staff time, third-party invoices and identifiable consumables against a project reference. For staff work, use a documented internal cost rate. A selling rate and an internal cost rate serve different purposes; do not substitute one for the other without explanation.
| Activity | Evidence to collect | Boundary to state in the quote |
|---|---|---|
| Project samples | Dispatch cost, preparation time and sample quantity | Included sample rounds and delivery destinations |
| Finish coordination | Meeting time and approved deliverables | Product matching support and approval responsibility |
| Technical administration | Document collection time and external review fees | Document package and specialist review exclusions |
| Delivery service | Booking time and agreed transport charges | Delivery points, access assumptions and attendance |
| After-delivery support | Logged assistance time and agreed visits | Included support period and escalation contact |
Furthermore, distinguish information already available from work that the account specifically requests. Sending a current data sheet and preparing a project-specific document register should not automatically receive the same allowance.
Keep shared catalogue development outside a single project’s support estimate unless the finance team assigns it consistently. Conversely, log a dedicated buyer meeting against its project, including participating staff rather than meeting duration alone. Review time rates periodically, and distinguish actual external invoices from internal estimates. This makes the calculation explainable when two branches quote the same customer.
Test a Quote With an Explicit Example
Consider illustrative assumptions, not market benchmarks: an order produces $30,000 in sales revenue and carries $21,000 in landed material cost. Its material gross margin is $9,000, or 30% of sales. Suppose the team estimates $600 for samples, $1,000 for coordination, $500 for delivery administration and $300 for agreed follow-up support.
Those support costs total $2,400. Therefore, the worksheet’s project contribution after support equals $6,600, or 22% of sales. The calculation makes no allowance for other costs outside the stated scope and offers no guarantee of results.
Now consider a $1,500 discount with all costs unchanged. Revenue falls to $28,500, and the remaining amount falls to $5,100, approximately 17.9% of revised revenue. Before approving that discount, review whether the project scope or actual cost estimate changes. Do not claim that an expected repeat order has already recovered today’s support costs.
Match the Service Scope to the Buying Channel
A building contractor may need room-specific coordination and a delivery sequence. A regional dealer may instead need product data, consistent packing identification and consolidated shipments. However, channel labels do not prove service demand. Ask each buyer what the team must deliver and record the answer.
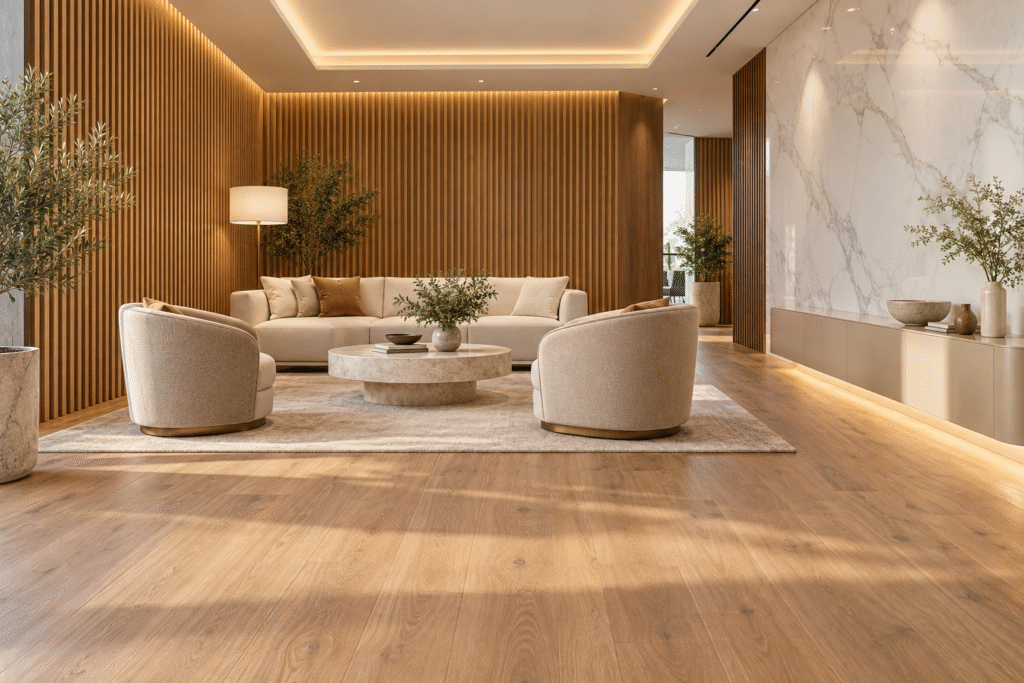
For example, a completed materials consultation lounge could combine SPC flooring, interior WPC wall panels and a UV marble-look feature wall. A contractor sourcing that palette may request coordinated references across all three products. Price the promised coordination explicitly, whether the quotation bundles it into the material price or shows a separate service line.
In addition, distinguish product advice from design responsibility. The decorative building materials supplier can provide technical specifications, but the project team must identify required approvals and the requested fire rating. Buyers should verify test reports, VOC limits, fire-rating documents and warranty terms for the exact products and application. Discuss durability, installation cost and maintenance cost without promising universal outcomes.
Give Sales Teams Clear Discount Authority
Create an internal approval rule around the defined contribution measure and the reliability of its inputs. For example, a salesperson may quote within an approved scope and price range, while a manager reviews lower contributions or uncertain support requirements. Set thresholds from the company’s actual economics, not an assumed industry margin.
Similarly, require the reviewer to see the proposed discount amount, service commitments and cost basis together. A concession on materials should not silently include extra coordination or another site visit. If the buyer requests additional support before accepting the quote, revise the estimate and show the revised offer clearly.
Then record who approved the price and which version the buyer accepted. This simple record helps the service team understand the promise and helps sales explain the basis for future quotations.
Separate First-Order Work From Repeat Support
Some project procurement work may occur once, such as organizing an initial finish approval. Other work repeats with each release, including order administration and delivery scheduling. Consequently, identify both categories before offering a repeat-order price.
After completion, compare estimated and actual support by activity. Investigate differences through the work record rather than automatically blaming the customer. Perhaps the team reused an approved reference successfully; perhaps unclear internal ownership created duplicate coordination. Use that evidence to improve the next quotation.
Also, revisit MOQ, lead time and container loading assumptions for each release. Repeat purchases can still involve different quantities, destinations or services. For custom colors and OEM/ODM cooperation, agree which development activities repeat and which existing approvals remain usable before confirming pricing.
B2B Buyer FAQs
Is Material Gross Margin the Same as Project Contribution?
No. In this worksheet, material gross margin deducts the defined landed material cost from revenue. Project contribution after support also deducts identified project support costs. Neither figure automatically represents company profit.
Must Every Support Activity Appear as a Separate Charge?
No. A distributor may bundle agreed support into its price. However, the internal calculation should still capture its cost, and the customer should understand the included service scope before accepting the quotation.
Should a Large Contractor Always Receive a Lower Price?
Assess quantities, service requirements and recorded costs together. A larger order may distribute some fixed project work across more material, but additional support can offset that advantage. Use the account’s evidence rather than a blanket rule.
How Can a Distributor Start Without Detailed Time Records?
Track a small number of activities on new quotations and label initial allowances as estimates. Then review actual sample dispatches, meeting time and delivery coordination. Improve the estimates as records accumulate instead of presenting early figures as proven costs.
What Should a Bulk Inquiry Tell the Supplier?
Send quantities, destination, product references and required support. Ask Witopdecor for a project quotation with clear supply boundaries. Request samples and technical data sheets for sample evaluation, and identify any finish coordination or delivery services in the bulk order inquiry.
James is a content creator and decorator with five years of experience designing home decor. In his daily life, james is constantly on the lookout for the latest, great examples of house design and further optimizes his solutions. Additionally, he writes articles related to outdoor design, interior design, and architectural decorating materials to help brands build more engaging relationships with their audiences.